A first coding of twelve public AI infrastructure projects, and the user contract that is still missing.
I am trying to follow an announced AI investment until I can name the person who can use the computing power. On 13 October 2026 I put twelve public projects in Korea, the Gulf, and the United States into one record. The record has eight stages: announcement, finance, equipment, power and permitting, construction, energization, commissioning, and external access. I mark a stage confirmed only when a dated public document establishes it. A plan, an authorization, a design review, a target date, or an analyst estimate stays partial. A blank means I did not find the record. It does not prove that the event never happened.
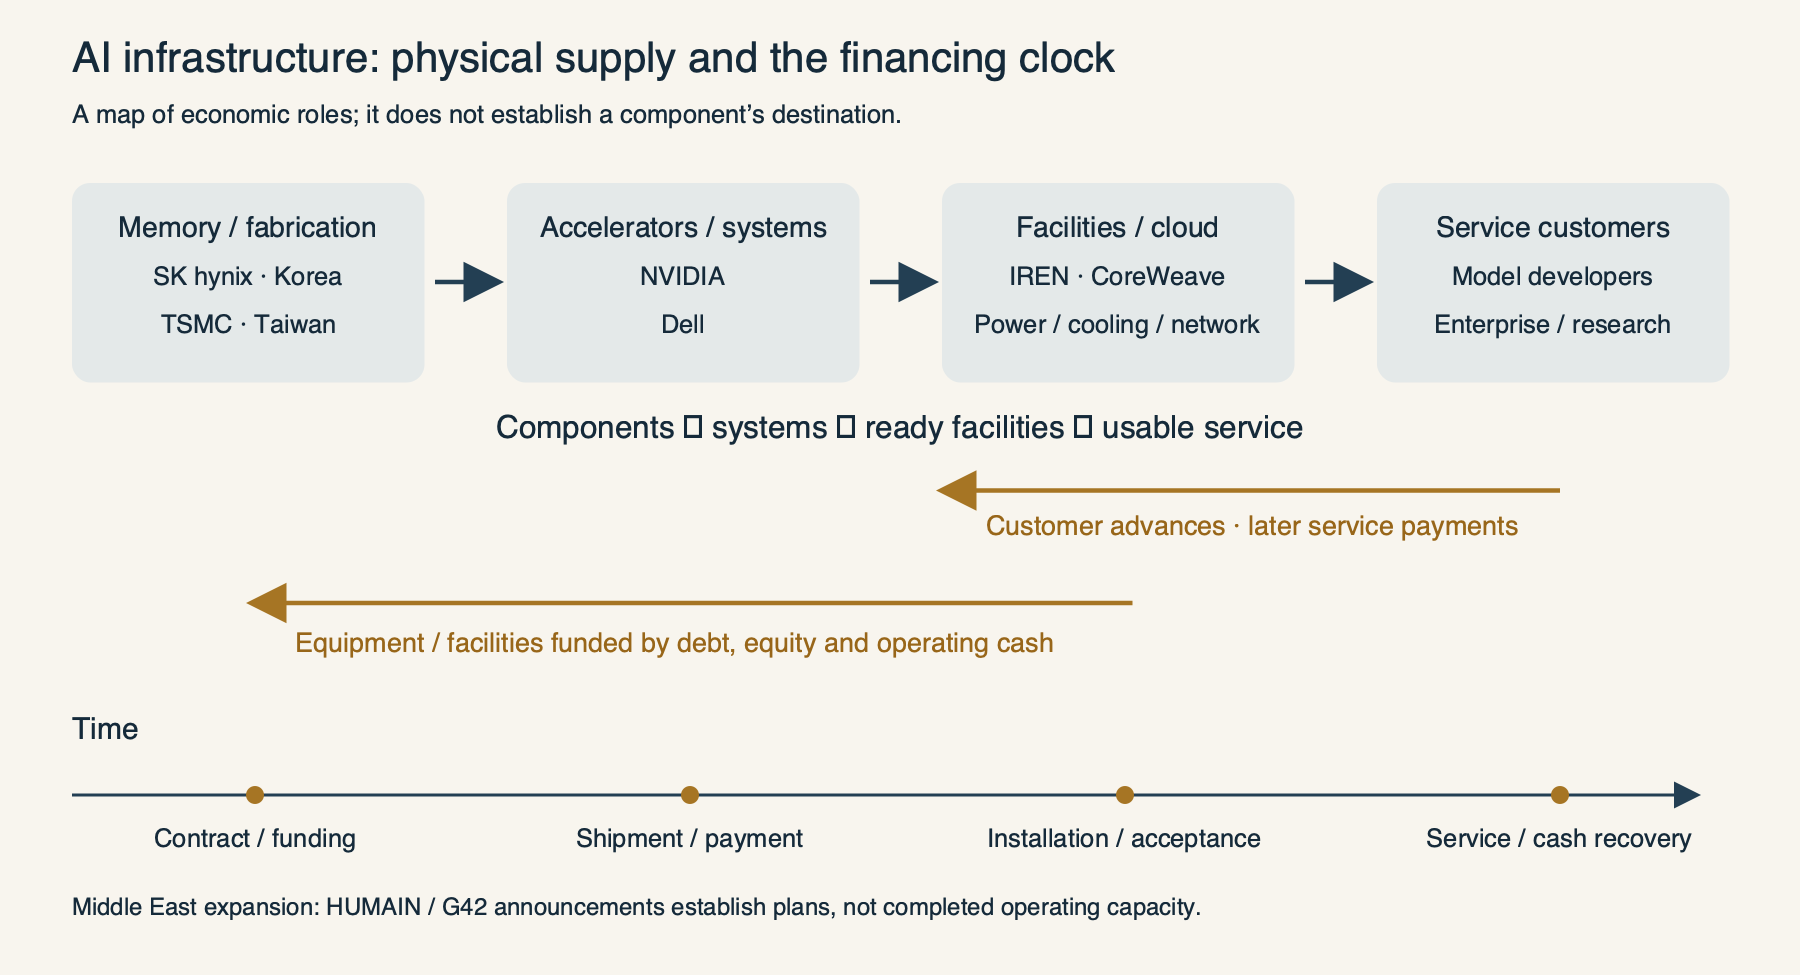
Ten projects have a confirmed announcement. Three have confirmed construction. None has a confirmed financial close, equipment delivery, energization, commissioning record, or contract that states who receives how much compute, at what price, and for how long.
| Project | What is public | What I can confirm | What remains open |
|---|---|---|---|
| NHN Yangpyeong, Seoul | 7,656 Nvidia B200 GPUs; 6,120 assigned to government-led use | Company statement of operation and priority supply from 1 April 2026 | Price, term, and named user contract |
| Naver-Brookfield | Up to $9 billion for 200 MW | July 2026 plan and division of roles | Close, power, construction, user |
| Shinsegae-Reflection | 250 MW memorandum; at least KRW 10 trillion expected | March 2026 memorandum | Site, power, procurement, user |
| SK, GS, and Naver bundle | 8.4 GW by 2029; about KRW 550 trillion planned | 29 June 2026 government briefing | Close, groundbreaking, user |
| Stargate UAE | 1 GW announced; first 200 MW targeted for Q3 2026 | May 2025 announcement; December 2025 construction report | Energization after the target quarter |
| HUMAIN | PIF national AI company; chip partnerships | 13 May 2025 announcement | First-facility commissioning |
| Khazna QAJ01, Ajman | 100 MW IT load; utility named | Construction progress; December 2026 target | Completion and energization |
| DataVolt Oxagon | 1.5 GW campus; $5 billion initial phase stated | 10 February 2025 land agreement | Grid connection and construction |
| Khazna Dammam | 200 MW; land reported | Site identification in the July 2026 audit | Power path |
| Stargate Abilene | About 0.3 GW estimated operating | Construction from Q2 2024; Epoch estimate of 17 April 2026 | Utility certificate and outside access |
| Stargate Shackelford | About 2 GW projected | Construction from Q3 2025; current capacity reported as zero | Energization |
| Siada, Ras Al Khaimah | Hourly B200 access claimed | Secondary announcement of 6 July 2026 | Capacity, price, and utility record |
The counts make the shape visible. Announcement is crowded. Access is empty.
| Stage | Confirmed | Partial | No public evidence located |
|---|---|---|---|
| Announcement | 10 | 2 | 0 |
| Finance | 0 | 7 | 5 |
| Equipment | 0 | 6 | 6 |
| Power and permitting | 0 | 4 | 8 |
| Construction | 3 | 2 | 7 |
| Energization | 0 | 3 | 9 |
| Commissioning | 0 | 3 | 9 |
| External access | 0 | 3 | 9 |
Korea: a national target, a company plan, and one operating claim
The largest Korean number comes from the government briefing on 29 June 2026. The government said SK, GS, and Naver would lead an 8.4 GW first phase by 2029, with a plan of about KRW 550 trillion, including investment still to be attracted. Groundbreaking is targeted for the first half of 2028. Data Center Dynamics described the figure as a gathering of plans already associated with Ulsan, Donghae and Dangjin, and Sejong. I keep that number as the state's target. I do not read it as closed money or as a facility a researcher can apply to use.
Beside it are two company plans. In July 2026 Brookfield said it would provide up to $9 billion for a Naver AI factory aimed at 200 MW. The interview names the roles. It does not name a close, a chip delivery, or a power agreement. Shinsegae and Reflection AI signed a memorandum in San Francisco for 250 MW, with an expected cost of at least KRW 10 trillion. The memorandum records an intention to secure land and build. It does not publish the site or the user.
The closest Korean operating claim is NHN. On 13 May 2026, NHN Cloud said it had built 7,656 Nvidia B200 GPUs at its Yangpyeong data center in Yeongdeungpo-gu, Seoul, with liquid cooling and a cluster of about 4,000 GPUs. Of those 7,656 GPUs, 6,120 are planned for projects led by the Ministry of Science and ICT. NHN said it had begun priority supply of some resources to industry, academia, and research institutes on 1 April 2026. The project sits inside the ministry and NIPA program for strengthening the use of AI computing resources. ZDNet's 29 July 2025 account of the operator selection matches the same split: NHN was assigned 7,656 B200 GPUs, of which 6,120 were the government share, within a larger 13,136 GPU program running through 2030. Users were to apply through an integrated platform and receive an allocation after review.
I can now name the ministry, the operator, the chip, the count, and the government share. I still cannot name the price or the term. The ministry press pages exist, including the operator selection notice and the notice that secured GPUs would begin supporting industry, academia, and research. The pages I opened did not display the attached announcement text or a user agreement. NIPA describes the procurement budget for the operator track as KRW 1,399,875 million. That is a budget for securing and operating GPUs. It is not an invoice showing what an outside user pays per hour.
The Gulf after the third quarter of 2026
Stargate UAE was announced in May 2025 as a 1 GW cluster, with a 200 MW first phase. On 5 December 2025, The National reported more than 5,000 workers, more than 100,000 cubic metres of concrete, and a statement that the first phase would be ready in the third quarter of 2026. The same article reported an export authorization for G42 to purchase the equivalent of up to 35,000 Blackwell chips. An authorization states what may be purchased. It does not record delivery.
I looked for a record after that quarter. A project tracker computed on 12 October 2026 still lists the first 200 MW energization as expected on 30 September 2026, not achieved. Its newest schedule source remains the 5 December 2025 article. The tracker also states that no committed capital is evidenced on the entity roles it records. I therefore leave energization and external access unconfirmed. Silence after a target date is a reason to look for the next document. It is not, by itself, proof that construction stopped.
QAJ01 is further along and still short of completion. Madar Strategy's audit of 22 July 2026 records groundbreaking in October 2024, completed steel by April 2025, a 100 MW IT load, and Etihad Water and Electricity as the named utility. Uptime Institute certified the design documents in February 2026. Data Center Dynamics later repeated Khazna's statement that the initial phase is due for completion in December 2026. As of 13 October 2026, that sentence is still a due date. December has not arrived, and I have not found a document saying the phase was completed early. Design certification and a completion target leave energization for a later record.
DataVolt's 10 February 2025 agreement with NEOM establishes a land lease and infrastructure support for a 1.5 GW campus, with an initial phase investment stated at $5 billion and operation expected in 2028. HUMAIN and Khazna Dammam remain in my August coding as announcement and site records. I did not reopen their primary documents for this pass, and I do not add their megawatts together. Siada's 6 July 2026 claim of hourly B200 access still has no public capacity, price, or utility record.
The United States comparison
Epoch AI's review of 17 April 2026 estimates that Abilene is operating at about 0.3 GW, with construction from the second quarter of 2024 and about four of eight buildings in service. The named workload is OpenAI's. Shackelford has construction from the third quarter of 2025 and a reported current capacity of zero. OpenAI's 21 January 2025 announcement said the program intends to invest $500 billion and begin deploying $100 billion immediately. That is the program's opening statement. A site level close for either Texas project still needs its own document.
The contract I could not fill in
I made a separate sheet for the sentence I wanted to find: who receives how much compute, at what price, and for how long. This is the sheet after the document search. It is not a reconstructed contract.
| Project | User named | Quantity | Price | Term | Result |
|---|---|---|---|---|---|
| NHN Yangpyeong | Industry, academia, and research institutes; 6,120 GPUs planned for ministry-led projects | 7,656 B200 GPUs installed, per NHN | Not found | Priority supply said to have begun 1 April 2026; program described through 2030 | Partial allocation, no price |
| Naver-Brookfield | Not found | 200 MW planned | Not found | Not found | Plan only |
| Shinsegae-Reflection | Government and enterprise clients intended | 250 MW planned | Not found | Not found | Memorandum only |
| SK, GS, and Naver bundle | Not found | 8.4 GW targeted | Not found | Operation targeted from 2029 | National target |
| Stargate UAE | US companies mentioned in secondary descriptions | 200 MW phase targeted | Not found | Q3 2026 target unmet in the October tracker | No access contract |
| HUMAIN | Not found | Overlapping announcements, not added | Not found | Not found | No access contract |
| Khazna QAJ01 | Not found | 100 MW IT load | Not found | December 2026 completion still due | No access contract |
| DataVolt Oxagon | Not found | 1.5 GW campus | Not found | 2028 target | Land agreement |
| Khazna Dammam | Not found | 200 MW, measure undefined | Not found | Not found | Site record |
| Stargate Abilene | OpenAI workload identified | About 0.3 GW estimated | Not found | Not found | Anchor use, no outside contract |
| Stargate Shackelford | OpenAI identified as the intended workload | Zero current capacity reported | Not found | Not found | Under construction |
| Siada | Free zone businesses, by company claim | Not disclosed | Not found | Hourly rental claimed | Unverified claim |
The missing price is the same kind of gap across the sample. NHN has the most specific public allocation, and even there I can read who the intended class of user is without learning what that user pays or how many hours they receive. Abilene has the clearest operating estimate, and its named user is the anchor customer. Stargate UAE has the most visible construction report, and the October tracker still has its first energization milestone marked expected.
The next documents are now narrower. I need the attached text of the ministry announcements, a post September 2026 energization notice for Stargate UAE, a completion or energization notice for QAJ01 after December 2026, and one user agreement that states quantity, price, and term. Until that agreement is public, I will keep announced gigawatts in the target column and usable access in its own column.
Evidence reviewed through 13 October 2026. HUMAIN and Khazna Dammam were not reopened against primary documents in this pass. The stage counts come from the pilot workbook, not from an inventory of all announced AI infrastructure.